Inside This Article:
- A couple was recently awarded $16 million after suing a Kansas City bar where the man allegedly fell from a mechanical bull.
- Before the trial, the couple sought $8 million to settle the case, while the defendants offered $2.2 million, according to Missouri Lawyers Media.
- Commercial General Liability (CGL) Insurance can cover customer injury claims; however, activities such as mechanical bull riding may require additional coverage.
- Businesses that add new attractions or change operations should discuss policy exclusions and coverage limits with a specialized Hospitality Insurance broker.
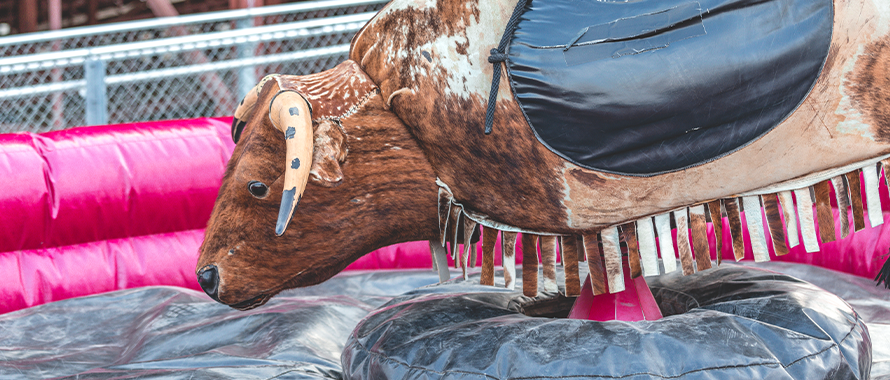
A night out at a cowboy-themed Kansas City bar turned into a multimillion-dollar liability case after a customer was thrown from a mechanical bull and allegedly suffered a severe injury. The man who fell was recently awarded $15 million for his injuries, with another $1 million awarded to his wife. The man claimed that his January 2022 pelvic injury at PBR Big Sky was caused by the bull’s lack of a seat or saddle, Missouri Lawyers Media reported Sept. 3.
Attorneys for the business argued that other falls that evening caused his injuries and that the bull could not have generated enough force to cause them, according to the report. The Jackson County jury, which returned its verdict Aug. 4, awarded the wife $1 million for loss of consortium, compensating her for the alleged harm his injuries caused to their marital relationship.
Costly injury claims and lawsuits against businesses are “more common than you may think,” said Ian Stamp, Senior Underwriter, Commercial Insurance, Atlantic Division, Burns & Wilcox, Canada Division, St. John’s, Newfoundland and Labrador. “It can be very damaging for the business.”
Commercial General Liability (CGL) Insurance can help cover legal defense, settlements, and other costs related to injury-related lawsuits. The rise in nuclear verdicts — those with awards totaling $10 million or more — also makes Excess Liability Insurance especially important, particularly for businesses offering amusement devices like a mechanical bull. Before the trial, the couple sought $8 million to settle the lawsuit, while the defendants offered $2.2 million, Missouri Lawyers Media reported.
“Based on some of the nuclear claims that have come out of that state, it is not surprising,” said Anthony Kobets, Senior Broker, Commercial Insurance, Burns & Wilcox, Kansas City, Kansas. “Anytime you have an amusement device where you have alcohol exposure as well, a larger claim is more likely.”
Anytime you have an amusement device where you have alcohol exposure as well, a larger claim is more likely.
Entertainment can create coverage gaps
In the recent Missouri case, the man’s injuries reportedly required surgery that involved hardware and pins, and his projected care needs included nearly $3 million for future medical care plus $460,000 for future household services.
Mechanical bull injuries have prompted lawsuits at other establishments, as well. In New York, a woman sued Johnny Utah’s in Manhattan alleging that a 2017 fall from its mechanical bull left her with a torn ACL, FindLaw reported at the time. Her lawsuit claimed that employees let her ride despite her being “visibly intoxicated.”
While CGL Insurance can respond to customer injury claims, business owners should understand how their policies may address risks like alcohol service and participation in entertainment activities, Stamp said. As part of a comprehensive Hospitality Insurance program, businesses that sell alcohol typically need to carry Liquor Liability Insurance, while those offering mechanical bull rides or other activities should confirm their policies include Injury to Participants Coverage. This can be added to a CGL policy in some cases, but it may need to be purchased separately, he said.
“If you have some special aspect to your business, like a mechanical bull, indoor batting cages, golf simulators, or axe throwing, you want to ensure that is covered,” Stamp said, adding that without the right coverage in place at the time of a loss, a business owner could face substantial out-of-pocket costs. “You cannot go back in time once a loss has occurred. It is just too late. You cannot change the coverage you have in place.”
If you have some special aspect to your business, like a mechanical bull, indoor batting cages, golf simulators, or axe throwing, you want to ensure that is covered. You cannot go back in time once a loss has occurred.
Understanding your coverage is critical, said Kobets. He said he recently helped place insurance for a Nebraska venue whose CGL Insurance and Liquor Liability policy terms excluded the business’s mechanical bull. A separate CGL policy for the device was secured, he said.
“It is about providing the options so that the insured can make an informed decision on how they want to operate,” Kobets said. “There are more exclusions on policies today than when I first started in the industry. You have to be very careful with reviewing forms and not just pushing paper.”
Large losses may exceed policy limits
In August, a Nevada jury awarded $56.5 million to a man who suffered a traumatic brain injury following a confrontation at a bar in Las Vegas and claimed that security staff failures contributed to the incident, KSNV reported. Earlier this year, a jury awarded a $6.3 million verdict to a customer who was seriously injured after falling over a low handrail at a restaurant in the U.S. Virgin Islands, the Virgin Islands Daily News reported in February.
Excess Liability Insurance can provide additional liability limits above underlying policies. “Expenses related to a claim can be very costly, and settlement can be a lengthy process,” Stamp said. “That can really impact the health of a business in the event of a loss.”
Hospitality businesses with security staff may also need Forcible Eviction Coverage. “If you employ bouncers, door staff, or security guards, or if your business is a bar, you may want to have that type of coverage added on to your CGL Insurance,” he said.
Finding coverage for hospitality businesses with unique entertainment risks can take specialized market knowledge, Stamp said, and owners should ask prospective brokers about their experience with similar businesses and hospitality claims. “It is definitely becoming harder to find coverage for these types of risks, but it is not impossible,” he said. “That is why it is very important for business owners to partner with experienced brokers.”
New attractions bring updated risks, coverage needs
Special events and interactive attractions can also introduce risks that differ from a restaurant’s everyday operations. Even moving tables to accommodate a DJ and dancing should prompt a conversation with the insurance broker, Stamp pointed out.
“If your broker is only providing coverage for a restaurant, that type of exposure is different and can potentially lead to gaps in coverage,” he said. “Being in contact with your broker about any changes throughout the policy term is very important.”
Being in contact with your broker about any changes throughout the policy term is very important.
Insurers often look closely at a hospitality business’s operations, including its hours, alcohol sales, and entertainment attractions. When entertainment activities are offered, owners should consult a legal expert about their risks, including whether waivers or hold-harmless agreements are needed and what liability limits are appropriate, Kobets said.
In this era of nuclear claims and payouts, you have to go through and talk with a legal expert to determine what is needed.
“They should definitely reach out to a legal expert,” he said. “In this era of nuclear claims and payouts, you have to go through and talk with a legal expert to determine what is needed.”