Inside This Article:
- Heavy snowfall, wind, and ice from a major Northeast blizzard in February is expected to cost up to $38 billion, including costly residential damage claims.
- Ice dams, roof collapse, and slippery walkways are among the risks homeowners face after severe winter storms.
- Damage related to blizzards is typically covered under Residential Property Insurance, though policies may respond differently depending on the type of loss.
- Icy conditions can increase the risk of slip-and-fall accidents outside of residential properties, potentially creating liability exposure for homeowners.
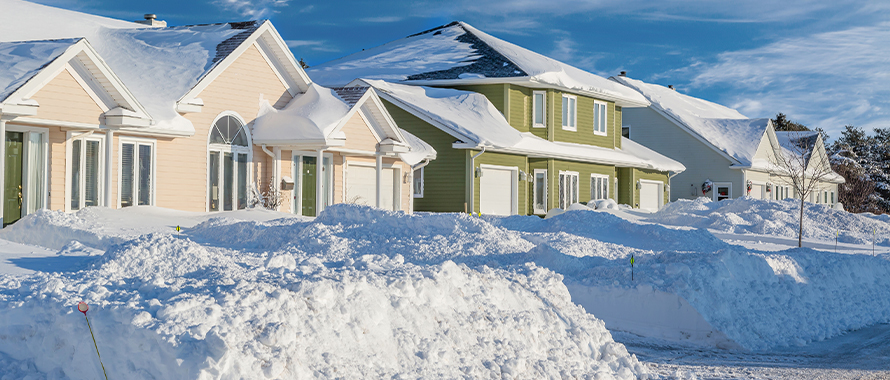
A historic blizzard that buried parts of the Northeast U.S. under several feet of snow is expected to carry a significant financial toll. AccuWeather estimates the Feb. 22 to Feb. 24 storm caused between $34 billion and $38 billion in total economic loss, making it one of the costliest winter weather events in recent years.
The storm brought heavy snowfall, powerful winds, and widespread power outages across multiple states, with at least 18 Northeast cities seeing official blizzard conditions and some areas accumulating more than 2 feet of snow within a short period. High winds during the storm reportedly reached hurricane strength in places like Cape Cod and Nantucket, while contractors in New York have seen a surge in demand for roof work as homeowners battle ice dams.
The combination of unusually heavy snowfall and powerful winds can increase the likelihood of costly property damage claims, particularly in areas unaccustomed to such extreme winter weather.
From roof stress to water intrusion and hazardous walkways, winter storms can present a range of risks for homeowners. Property damage and liability claims related to winter storms can generally be covered under Residential Property Insurance, also known as Homeowners Insurance, though severe slip-and-fall claims could necessitate additional liability coverage through a Personal Umbrella Insurance policy.
“This winter has definitely been more impactful than prior years. We are used to snow here, but not necessarily on the level of more than 20 inches,” said Drew Bonocore, Senior Underwriter, Personal Insurance, Burns & Wilcox, New York, New York. “The losses could definitely be significant, especially with all the types of Homeowners Insurance claims that could come into play from storms like this. There is often a hyper-focus on hurricanes, but these winter storms can also bring high winds, as we saw with this storm.”
There is often a hyper-focus on hurricanes, but these winter storms can also bring high winds, as we saw with this storm.
Risk of ice dams, roof stress after heavy snowfall
Large snowstorms can pose several structural challenges for homes, especially roofs, including ice dams — ridges of frozen water along rooflines that can trap melting snow and lead to water seepage into ceilings and walls. After a winter storm in Connecticut earlier this year, roofing companies received an influx of calls from homeowners regarding ice dams and interior water damage, WFSB-TV reported, and one homeowner told the news outlet that she needed to replace her roof last year due to damage from ice dams.
Ice dams form when melting snow refreezes along roof edges, creating a barrier that prevents water from draining properly into gutters. As water accumulates behind the ice, it can seep beneath roofing materials and enter the home, potentially damaging ceilings, walls, and insulation.
When ice dams build up amid continuously cold temperatures, the risk of water damage increases, Bonocore said. This is particularly concerning for secondary or seasonal homes, where problems may not be noticed until the damage is more severe. “If you have a secondary property that is unoccupied during the storm, that location should be checked on by the insured or by a suitable individual or caretaker,” he said.
Frozen pipes, damage from fallen trees, and broken windows are among other winter storm perils for homeowners. In severe cases, heavy snow accumulation can also lead to roof collapse, particularly when large amounts of heavy, wet snow fall within a short period and place sudden stress on a home’s structure.
“When you get a lot of snow in a very short period of time, a roof can be weighed down by that sudden influx of heavy, wet snow,” he said. “It can be rife for collapse.”
How insurance may respond to winter storm exposures
Severe winter weather can lead to costly insurance claims for homeowners. A winter storm that hit parts of the Eastern and Southern U.S. earlier this year resulted in about $6.7 billion in privately insured losses, according to catastrophe modeling firm Karen Clark and Company, Reuters reported Feb. 3.
Many types of winter storm losses can be covered under a standard Homeowners Insurance policy, including damage from wind, heavy snow, frozen pipes, and other sudden and accidental events. However, coverage depends on the policy’s specific terms, conditions, and exclusions. Homeowners should review their policies with their insurance agents to understand which losses are covered and where potential gaps may exist.
While smaller losses such as food spoilage can occur due to storm-related power outages, Homeowners Insurance is primarily intended to provide financial protection against significant losses that may be difficult for homeowners to absorb on their own.
Some perils may require separate coverage, Bonocore pointed out, including coverage for flood and mold. “Flood is generally excluded on a Homeowners Insurance policy, therefore a separate Flood Insurance policy would be needed for that peril,” he said. “Mold claims can also occur from the melting snow and ice, and that is a separate coverage you can purchase via endorsement.”
In addition to carrying insurance, homeowners can help protect against severe losses by mitigating prior to storm damage rather than once it is discovered. Keeping up with regular home maintenance, having storm supplies readily available, and installing automatic water shutoff devices that monitor plumbing are all examples of mitigation, Bonocore said. “If the automatic water shutoff device detects a leak, it will cut off the water supply to the home,” he said.
Liability risks on icy property
Snow and ice removal are also critical, and homeowners should know that they can be held liable for slip-and-fall injuries that occur on their property due to dangerous conditions. With regard to liability, in addition to snow removal, it is recommended to apply salt/snow melt on all walkways and entryways to help prevent slip, trip, and fall claims that can occur post-storm.
Slippery sidewalks, driveways, and walkways can increase the potential for liability claims. Homeowners may be responsible for maintaining safe access to their properties for visitors, including neighbors and other guests. Requirements for clearing snow and ice from public sidewalks can vary by municipality, making it important for homeowners to understand their local obligations.
Liability limits on a standard Homeowners Insurance policy may not be sufficient to cover a severe slip-and-fall claim, making additional protection through a Personal Umbrella Insurance policy worth considering. Significant liability claims can create substantial financial exposure, potentially extending beyond a homeowner’s current assets to future earnings, depending on applicable state laws. Personal Umbrella Insurance can provide additional protection against these risks, often at a relatively modest cost compared to the potential financial consequences of a major claim.
These policies often range from $1 million to $5 million in additional liability coverage, Bonocore said. “We definitely encourage homeowners to explore that option,” he said. “It is important to work with your agent and understand how your policy works, what it covers and does not cover, and then the consumer can make an educated decision.”
It is important to work with your agent and understand how your policy works, what it covers and does not cover, and then the consumer can make an educated decision.