Inside This Article:
- A fire recently destroyed the historic Lochmoor Country Club clubhouse in Grosse Pointe Woods, Michigan.
- Historic properties may require specialized Commercial Property Insurance with Historical Replacement Cost to reproduce original materials, designs, and craftsmanship after a loss.
- Business Interruption Coverage and Extra Expense Coverage can help companies recoup lost revenue and maintain payroll during restoration.
- Updates to major building systems and safeguards such as sprinklers or fire-rated walls can help protect historic properties.
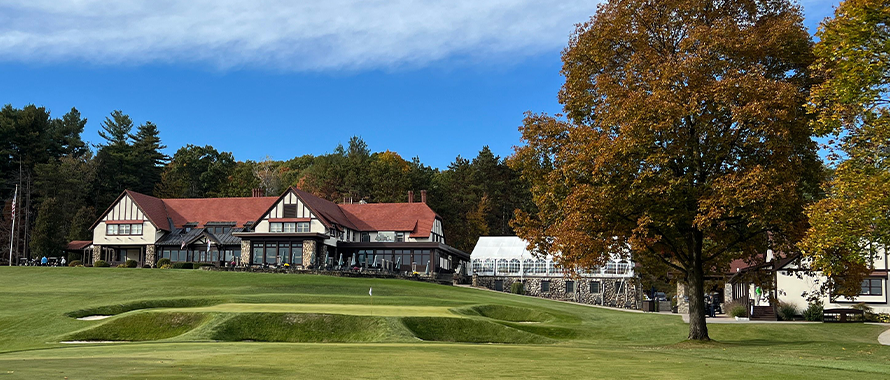
A fire that broke out at the century-old Lochmoor Country Club in Grosse Pointe Woods, Michigan, destroyed its historic clubhouse, including a newly renovated restaurant and bar area. The Sept. 9 blaze initially appeared contained to the attic before spreading through the roof and causing part of the structure to collapse, leaving the clubhouse a total loss, according to ClickOnDetroit. The cause remained under investigation, although officials said the fire may have originated in the kitchen.
The loss underscores a particular challenge for owners of historic commercial properties: rebuilding may involve far more than replacing walls and a roof, requiring specialized materials and craftsmanship. The private club has been part of the community since 1917, and the club’s president said Lochmoor intends to rebuild “stronger and better.”
“It is a travesty,” said Chantal Grumski, Senior Broker, Commercial Insurance, Burns & Wilcox, Detroit / Farmington Hills, Michigan. “Historical buildings are not just walls and windows; they are stories of the past. The positive side of it is that no one was hurt. Hopefully, they had the right insurance coverage in place to restore the building to its historical value.”
Historical buildings are not just walls and windows; they are stories of the past. … Hopefully, they had the right insurance coverage in place to restore the building to its historical value.
Historic commercial properties should be covered by a Commercial Property Insurance policy with an accurate valuation and, where available, Historical Replacement Cost Coverage that can help owners restore historical features after a loss. Accurate valuation is especially important for historic properties, which may have fewer carrier options available.
“This seemed to be a big part of the community, so it is a significant loss,” said Omar Martinez, Underwriter, Commercial Insurance, Burns & Wilcox, Orlando, Florida. “Whenever a historic building is involved, determining the correct value can be a challenge. If a property is on the historic registry, some carriers will be willing to write the property and others may not.”
[The clubhouse] seemed to be a big part of the community, so it is a significant loss.
Specialized coverage needed for historic buildings
Lochmoor is not the first historic golf club in Michigan to face a devastating fire. In February 2022, a blaze destroyed much of the century-old clubhouse at Oakland Hills Country Club in Bloomfield Township, Michigan, and caused an estimated $80 million in damages. In 2024, the historic Lutsen Resort lodge in Minnesota was destroyed by a “ferocious and violent fire,” Minnesota Public Radio reported at the time.
In many cases, restoring a historic property after this type of loss can require specialized artisans, custom designs, and materials sourced from around the world to reproduce certain architectural features, Grumski said. Historical Replacement Cost Coverage on a Commercial Property Insurance policy can help cover these costs, while standard Replacement Cost Coverage generally pays to rebuild using modern-day materials of like kind and quality and Actual Cash Value Coverage accounts for depreciation.
“The challenge in underwriting is ensuring that you are using Historical Replacement Cost as opposed to standard Replacement Cost Coverage,” she said. “We want to maintain those original historic features using specialized materials, designs, and craftsmanship. One program I work with will source products from anywhere in the world to restore that historical value.”
The challenge in underwriting is ensuring that you are using Historical Replacement Cost as opposed to standard Replacement Cost Coverage. We want to maintain those original historic features using specialized materials, designs, and craftsmanship.
Even with specialized coverage, accurate valuations are essential because certain original features may be difficult or impossible to reproduce.
“If there was specialized glass or stonework within the building, they might not always be able to rebuild it exactly as it was, but there should at least be a substitute if the valuation is high enough,” Martinez said. “Carriers want to insure a building to value. They do not want to underinsure it, but they also do not want to overvalue it.”
Ordinance and Law Coverage is another important consideration because reconstruction may trigger updated building code requirements that could increase the cost of restoration. Certain items may also require separate protection. “Historical artifacts, such as sculptures, artwork, or stained glass, can be placed on an Inland Marine Insurance policy,” Grumski said. “They may not necessarily be picked up on the package policy.”
Extended closures can strain finances
Commercial property fires can cause significant financial impacts outside of building repair expenses. A recent kitchen fire at Mia’s Table in Houston, Texas, has kept the restaurant closed for more than a month, according to reports, and in Connecticut, a steakhouse at a casino is aiming to reopen this fall after shutting down due to a fire almost a year ago.
In the recent Lochmoor Country Club fire, facilities destroyed included a newly renovated restaurant and bar area, ClickOnDetroit reported. The club also served as a venue for tournaments and other special events.
“They had an event coming up that weekend that they might not have been able to hold, and they also likely have employees they do not want to lose,” Grumski said. “Maintaining payroll can help make sure those employees are still able to pay their bills.”
Business Interruption Coverage may be included or added onto Commercial Property Insurance policies and can help replace lost income and pay operating expenses after a covered loss. Extra Expense Coverage can help cover other costs incurred in order to continue operating, such as renting temporary facilities or equipment.
“Golf courses often host Sunday brunch, holiday celebrations, and other special events,” Martinez said. “Coverage for business income is definitely something they would want to have.”
Golf courses often host Sunday brunch, holiday celebrations, and other special events. Coverage for business income is definitely something they would want to have.
To help determine how much coverage is needed, carriers will often review an organization’s revenue, payroll, and potential recovery time. “We have a worksheet that asks questions specific to the industry and helps identify exactly what the exposure is,” Grumski said. “The agent should discuss the potential losses with the insured.”
Lack of updates can narrow insurance options
The age, construction, and condition of a property can affect which insurance carriers are willing to insure it and what coverage terms are available. Some carriers may decline to insure buildings listed on a historic registry or require documentation of major system updates, Martinez said. Updates to a building’s roof, electrical, plumbing, and HVAC systems can also influence which coverage terms are available, such as Replacement Cost or Actual Cash Value.
“There is a misconception that you can get the best coverage on a really old building with no updates,” Martinez said. “To get that better coverage, you need to make those updates. It helps with the underwriting process and helps us find options for the client.”
When a historic building is reconstructed after a fire, the process could allow for the addition of safeguards such as sprinklers or fire-rated walls while maintaining its historical features, Grumski said. Protecting these properties requires collaboration among all parties, including the carrier, agent, and insured, she added.
“I think everyone should be involved,” she said. “We are a team. We all want to see the best outcome for the building, and we should work together to discuss the exposures and identify any coverage gaps.”